
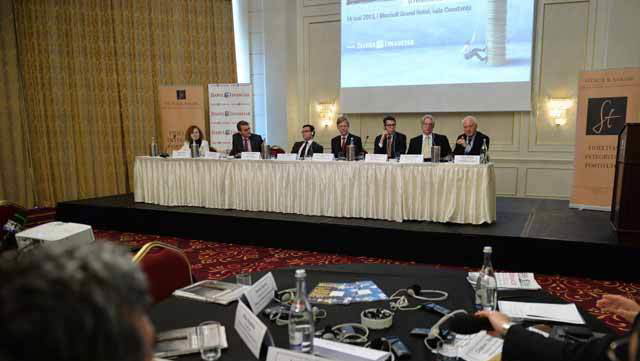
“The cheaper we can make loans the better, but I won’t cut interest rates because somebody says so. We are looking at whether the reference interest rate is going down. If there are no more players to drive deposit interest rates up, then loan interest rates will also be lowered. However, I don’t think the decline should be aggressive, but gradual,” van Groningen said at a seminar on restructuring of non-performing loans an on resuming lending, organized by ZF and law firm STOICA & Asociatii.
He answered a question on whether bankers would do what the governor of the Romanian central bank called on them to do, when he said “Bankers, cut interest rates if you want to sell loans”
The conclusion of Tuesday’s seminar is that banks will not resume lending before the economy is revived because the crisis-generated reticence is still strongly felt in the banking system. In addition, non-performing loans and the depreciation of guarantees weigh heavily on balance sheets and keep loan sales from rising.
“Statistically lending tends to be revived after the real economy rebounds. There is a delay of six months to a year between the two,” says Catalin Pauna, chief economist of the World Bank’s Bucharest representative office.
The talk on restarting lending before or after the economy recovers has often appeared in the last two years as the economy has failed to recover since the beginning of the crisis. Private lending stagnated in the last four years at the equivalent of EUR50 billion, with bankers preferring to redirect most of their resources to government securities.
After four years of crisis Romania’s gross domestic product (GDP) remains below the 2008 level, the last year of economic boom recorded in Romania.
The Romanian banking system recorded losses of around 3 billion lei in the last three years because of significant provisions set up in order to cover losses from non-performing loans. Banks’ capitals have thus been eroded, limiting their ability to generate new loans. An important role in the crisis was played by the depreciation of real estate assets that clients set up as loan guarantees.
“We have yet to put behind us that state of inhibition that the crisis generated in the last four years. Neither investors nor consumers or banks have managed to put this state behind them. But I think the banking sector will in the future offer us one of the most important answers to overcoming the current crisis because banks play a major part in the economy,” believes Valeriu Stoica, founding partner of law firm STOICA & Asociatii.
Banks have accumulated in their portfolios overdue installments and interest rates of almost RON30 billion. Van Groningen says though that the non-performance rate indicator – 19% at banking system level – is artificially inflated because the law doesn’t allow banks to write off loans with very significant payment delays.
“The level of non-performing loans is inflated by the fact that banks cannot write off loans without taking all the legal measures to recoup the loan, and more often than not there is no need for such measures.”
A major problem cited by bankers and lawyers present at the ZF seminar is that of insolvent firms, some of which go insolvent only to avoid paying their loans and not in order to find a solution to restructure.
“Sometimes clients go insolvent in order not to pay their loans. Us as a bank are trying to prevent that and are looking for restructuring solutions. Insolvency is not a solution because you lose a lot of your value and it takes a very long time,” said Jurgen Kristiaan de Ruijter, manager of the recovery and restructuring division within BCR.
The BCR official says an insolvency process can take between six months and a year and sometimes even a year and a half.
Insolvent firms had debts of around RON10 billion with banks at the end of March. These amounts went up eight-fold in one year.
The number of insolvent debtors was 2,200 companies at the end of March, while overdue amounts hit RON7 billion.
Milo Stevanovich, program manager within the International Finance Corporation, says in order to discourage fraud one needs to change the legislation, as well as use detection systems.
“Fraud detection systems are needed. There are fraud detection models because when you end up with a very large volume of data, it’s difficult to trace frauds without a model. I don’t think there is a perfect system, but one needs to discourage fraud,” Stevanovich says.
Gordon W. Johnson, president of EM Advisors LLP, an advisory firm based in Washington DC, says the economy does not have fuel for growth if lending is absent.
“If the non-performing loans ratio is high, lending stagnates and the economy has no fuel in its tanks. This is a downward spiral and a portfolio restructuring is needed to progress.”
The ratio of non-performing loans in the Romanian banking system was 19% at the end of March, one of the highest in the region.
(English version by Daniela Stoican)